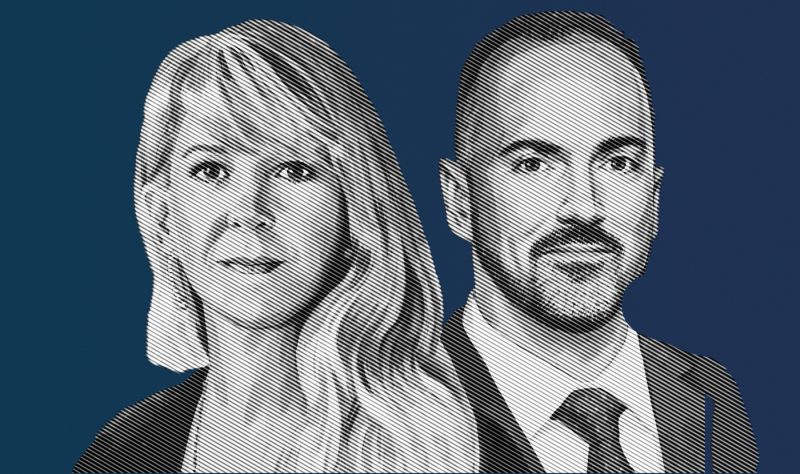

In one of the more instructive trading weeks of the year, the bond market delivered a lesson in both volatility and purpose. Liz Ann Sonders, Chief Investment Strategist at Charles Schwab, and Collin Martin, Director of Fixed Income Strategy, unpack the signals in the latest episode of On Investing 1 and the picture that emerges is one of a market undergoing a meaningful shift in how it prices risk, leverage, and quality.
When the 10-Year Took the Elevator
The week's drama began with a Consumer Price Index print that came in hotter than expected. The 10-year Treasury yield responded immediately. Martin describes the sequence plainly: "We saw the 10-year Treasury yield really bounce around... the movement started last Wednesday following the Consumer Price Index report that came in a little bit hot. We saw the 10-year Treasury yield jump sharply following that release, jumped about 14 or 15 basis points in a matter of minutes. It got as high as 5.32%."
What followed was equally instructive. The yield gave back the gains through the course of the session, ultimately closing near 5.07%, its lowest level in several weeks. The driver of that reversal was not renewed confidence in inflation, but growing anxiety about the sustainability of AI-related capital expenditure. "It took the elevator up, and then as the course of the day went on, it kind of took the escalator down," Martin observes.
Bonds Did Their Job
For investors still debating the relevance of fixed income in a portfolio, Martin offers a pointed reframe. The week's price action demonstrated precisely what bonds are supposed to do: decline in yield and rise in price as equities fell. "Last week, arguably, bonds did exactly what they're supposed to do, in that yields fell, their values rose because bond prices and yields move in opposite directions, as the stock market declined a little bit."
Sonders contextualizes the 60/40 debate with the same measured directness: even in periods when bond prices are under pressure, the income component of a fixed income allocation continues to accrue, and any security held to maturity returns its principal. "I think there's often a misunderstanding of how bonds work within a portfolio," she says. Martin extends the point by noting that current income levels are simply too attractive to dismiss: "You invest in a strategy that can offer you a 5% yield and then the values hold steady for a while... we're at a level right now where yields we think are very attractive."
The Leverage Problem Inside AI
The more consequential conversation concerns what is happening beneath the surface of the AI investment boom. Sonders draws a direct line between AI's capital intensity and the bond market's growing sensitivity to credit risk. She frames leverage as a financing-timeline problem: "leverage is really just... you're financing the timeline, the timeline meaning from when the investment is made to when it bears fruit."
The issue is that AI build-out cycles carry long duration characteristics while many companies funding them are doing so with shorter-dated, higher-risk debt. Neocloud companies, which rent GPU clusters primarily to AI developers, sit at the sharpest edge of this tension. "The neoclouds are arguably the most rate-sensitive corner of AI because they are long-duration growth companies, but they're funded with sort of short-fuse debt."
Martin distinguishes between the hyperscalers, which carry investment-grade ratings and diversified revenue streams, and speculative-grade issuers where leverage is already elevated and cash flows more volatile. "You can't necessarily paint the picture with a broad brush because not everyone is the same."
The Factor Rotation Underway
Sonders identifies a subtler but telling development at the factor level in equities. Looking beyond sector-level returns, what is working is quality. High interest coverage, low volatility, profit-margin stability: these characteristics are being rewarded. In the Russell 2000, profitable companies are outperforming non-profitable ones by 18 percentage points year to date, the reverse of last year's dynamic. "Now there is just this sort of hunt for quality in an environment where there's increase in concerns about earnings estimates, profit margin stability, the capex spend, how that capex is being financed."
What Comes Next
With the Federal Open Market Committee meeting ahead, Martin expects no change to the current 3.75% to 4.00% target range. Importantly, there will be no updated dot plot or economic projections. Attention will fall on whether the decision is unanimous and on how Chair Kevin Warsh characterizes the inflation outlook. "He wants to take a look under the surface about the share of subcomponents rising at a 3% annualized rate," Martin notes, referring to the diffusion index Warsh has emphasized. Schwab's base case: a pause this meeting, a hike in December, and another early in 2027.
GDP, PCE, housing data, and consumer confidence round out a data-rich week ahead. Sonders flags one structural nuance worth watching in the GDP release: AI-related capital goods are predominantly imported, which means the capex boom may be partially offset in the net-exports component. "That does not accrue to the benefit of GDP because it's a net-exports reading."
5 Key Takeaways for Advisors and Investors
- Bonds are still doing their job. The week's correlation between falling yields and falling equities demonstrated fixed income's diversification value in real time. Income at current yield levels remains a compelling standalone case.
- Quality is back in command. Factor leadership has rotated sharply toward high interest coverage, low volatility, and profit-margin stability. Screens filtering for quality now carry meaningful return differentiation, especially in small caps.
- AI leverage is a credit risk story. The distinction between investment-grade hyperscalers and speculative-grade neoclouds matters enormously in portfolio construction. Not all AI exposure carries the same risk profile.
- The FOMC is on hold, but not done. Schwab expects a December hike followed by another in early 2027. Inflation breadth, not the headline number alone, is the variable Chair Warsh is watching most closely.
- GDP interpretation requires nuance. AI capex that flows through imports will weigh on the net-exports component of GDP even as business investment readings remain strong. The headline number may understate or obscure underlying demand dynamics.
Footnote:
- Liz Ann Sonders and Collin Martin, On Investing podcast, Charles Schwab, October 2026. https://www.schwab.com/learn/story/can-bonds-still-do-their-job ↩︎