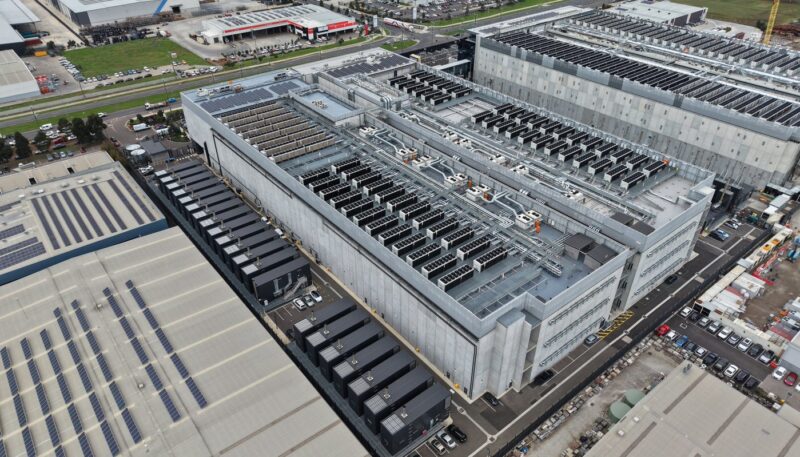

The prevailing picture of the AI infrastructure buildout is a straight line: more chips, more data centers, more gigawatts, financed without friction. Janus Henderson credit analyst James Donahue sees a more constrained path, and arguably a healthier one. In a recent Janus Henderson commentary1, Donahue frames the buildout through three bottlenecks. "Number one: Power. Number two: Permitting. And number three, and perhaps most overlooked: Paper." The argument is not that the buildout fails. It is that forces outside the builders' control are imposing discipline, and that discipline changes the shape of the entire cycle.
The Grid Has a Speed Limit
Power is the first gate. "We continue to believe that power is a key gating factor to this build-out," Donahue says. The arithmetic is stark. Some sell side estimates call for 36 GW of incremental power added in 2028, yet "The U.S. grid can generally only add 20 to 25." That leaves a shortfall of 11 to 16 GW.
Behind the meter solutions, such as energy cells or what Donahue calls "bring your own generator, so to speak," can address part of that gap, "but not all of it." To be clear, the escape valve has its own lock. Those workarounds, he notes, "come with their own litany of regulatory issues," which leads directly to the second P.
Not Within Ten Miles of Here
Permitting is where engineering meets the neighbours. Donahue observes that "while these projects may ultimately go through, they're being hit with a series of delays," driven in part by local constituents "not being super thrilled about the technology being within a five-to-ten-mile radius of them."
His case study is Project Jupiter, a 2.1 GW project in Doña Ana County in southern New Mexico, which ran into a series of delays tied to the pipelines surrounding and feeding the site. The conclusion is plain: "And as a result, delays are sort of inherent to this build-out as well."
The Paper Wall
The third P is the one Donahue believes the market underrates. "Ultimately, our view is that the broader market just expects the debt market to absorb this paper. We think it may be a little more nuanced than that."
Hyperscaler related debt issuance is on track to land around $275 billion this year, while some on the street expect more than $400 billion next year, a step up of roughly 45%. "So that's a big step up in a market that's already fairly saturated with this paper." That figure excludes GPU related financing entirely. Donahue suggests fixed income investors may hit a ceiling on how much AI and hyperscaler exposure they can hold, forcing capital to come from elsewhere. "Namely the equity market or perhaps even governments."
For credit investors, this is the crux. Absorption capacity is not infinite, and concentration limits are real.
Discipline by Necessity
Taken together, the three bottlenecks make this cycle "a lot more complicated and challenging than previous cycles." Donahue puts it bluntly: "In other words, the builders here have to be disciplined not because they want to, but because they have to."
Here the view turns quietly contrarian. Constraints that look like headwinds may function as shock absorbers. A slower buildout, "which in our view is a good thing," carries a symmetrical benefit. "A less steep build out and a less steep upcycle could ultimately beget a less steep downcycle, should that occur." Note the honesty of that final clause. No downturn is forecast; the point is that its amplitude may be smaller.
Incumbency Has a Premium
The final insight follows logically. "If it's harder to add one net new GW, then your existing one GW sees more demand." Scarcity accrues to what is already plugged in: power shell providers, owners of existing grid connections, and the GPUs slotted into those data centers. Looking to where the puck is going, value may sit less with the next project and more with the capacity already standing.
Key Takeaways for Advisors and Investors
- Watch the power gap. Projected demand of 36 GW against grid additions of 20 to 25 GW is a checkable constraint on buildout timelines.
- Price in permitting delays. Local opposition and pipeline issues, as at Project Jupiter, make delays structural rather than incidental.
- Monitor issuance capacity. A move from roughly $275 billion to more than $400 billion in hyperscaler debt tests fixed income appetite, especially before GPU financing is counted.
- Reframe the slowdown. A disciplined, less steep upcycle may reduce downside amplitude, which is constructive for credit holders.
- Favour incumbents. Existing grid connections and power shell capacity gain value as new capacity becomes harder to add.
Footnote:
1 Donahue, James. "Power, Permitting, and Paper: The 3Ps Behind the AI Infrastructure Buildout." Janus Henderson Investors, www.janushenderson.com/en-us/advisor/article/power-permitting-paper-3ps-behind-the-ai-infrastructure-buildout/. Accessed 3 Nov. 2026.