
by Kristian Kerr, Head of Macro and Investment Strategy, LPL Research
Additional content provided by Brian Booe, Analyst, Research
Broadly speaking, the directional drivers for stocks in September could be boiled down to the oil market, the bond market, and central banks. And not surprisingly, all three can influence each other. As the Iran conflict stretched through a seventh month, correlation data for oil prices and the S&P 500 suggests that equity markets grew increasingly sensitive to swings in crude (and geopolitical updates) as investors weighed ramps in both kinetic activity and hopes for diplomatic resolution. And while headlines have and will continue to focus on oil prices, market focus may also be shifting one step deeper to refined product availability — and crack spreads are the clearest indicator.
For quick context, a crack spread is the difference between the price of crude oil and the value of refined products made from it, such as diesel or gasoline (crack refers to the refining process called cracking, where the molecular structure of crude or heavy oil is broken down using heat). They are commonly used as a proxy for refinery margins, but can also serve as a real-time indicator of fuel market tightness and supply-demand imbalances.
What’s Driving the Rise in Crack Spreads?
The historic spike in crude prices at the onset of the U.S.-Iran conflict has been a dominant story across capital markets since it began on the final day of February. Crack spreads followed the price of oil higher as shipping disruptions tied to the de facto closure of the Strait of Hormuz and refinery outages around the Persian Gulf due to air strikes tightened refined product supplies. More recently, attacks in the Red Sea shuttering the Saudi East-West pipeline helped spur another leg higher in both oil prices and crack spreads. Separately, creating somewhat of a “perfect storm” in helping exacerbate record crack spreads is the ongoing Russia-Ukraine war, in which Ukrainian drone strikes have disrupted Russian refining capacity and Russia’s diesel ban have further constrained global fuel supplies and supported refinery margins.
While there are different crack spreads for specific products, the most notable has been the diesel crack spread, which measures the difference between crude oil and diesel fuel prices. U.S. diesel crack spreads surged to a record high of $118.32 per barrel in mid-September, more than 2.8 times the daily average of $42.12 since 2022, surpassing the March record of $97.19, which bested the previous high from the early days of the war in Ukraine. European crack spreads have also surged to records of their own just below $100 per barrel.
U.S. Diesel Crack Spread Hits an All-Time High
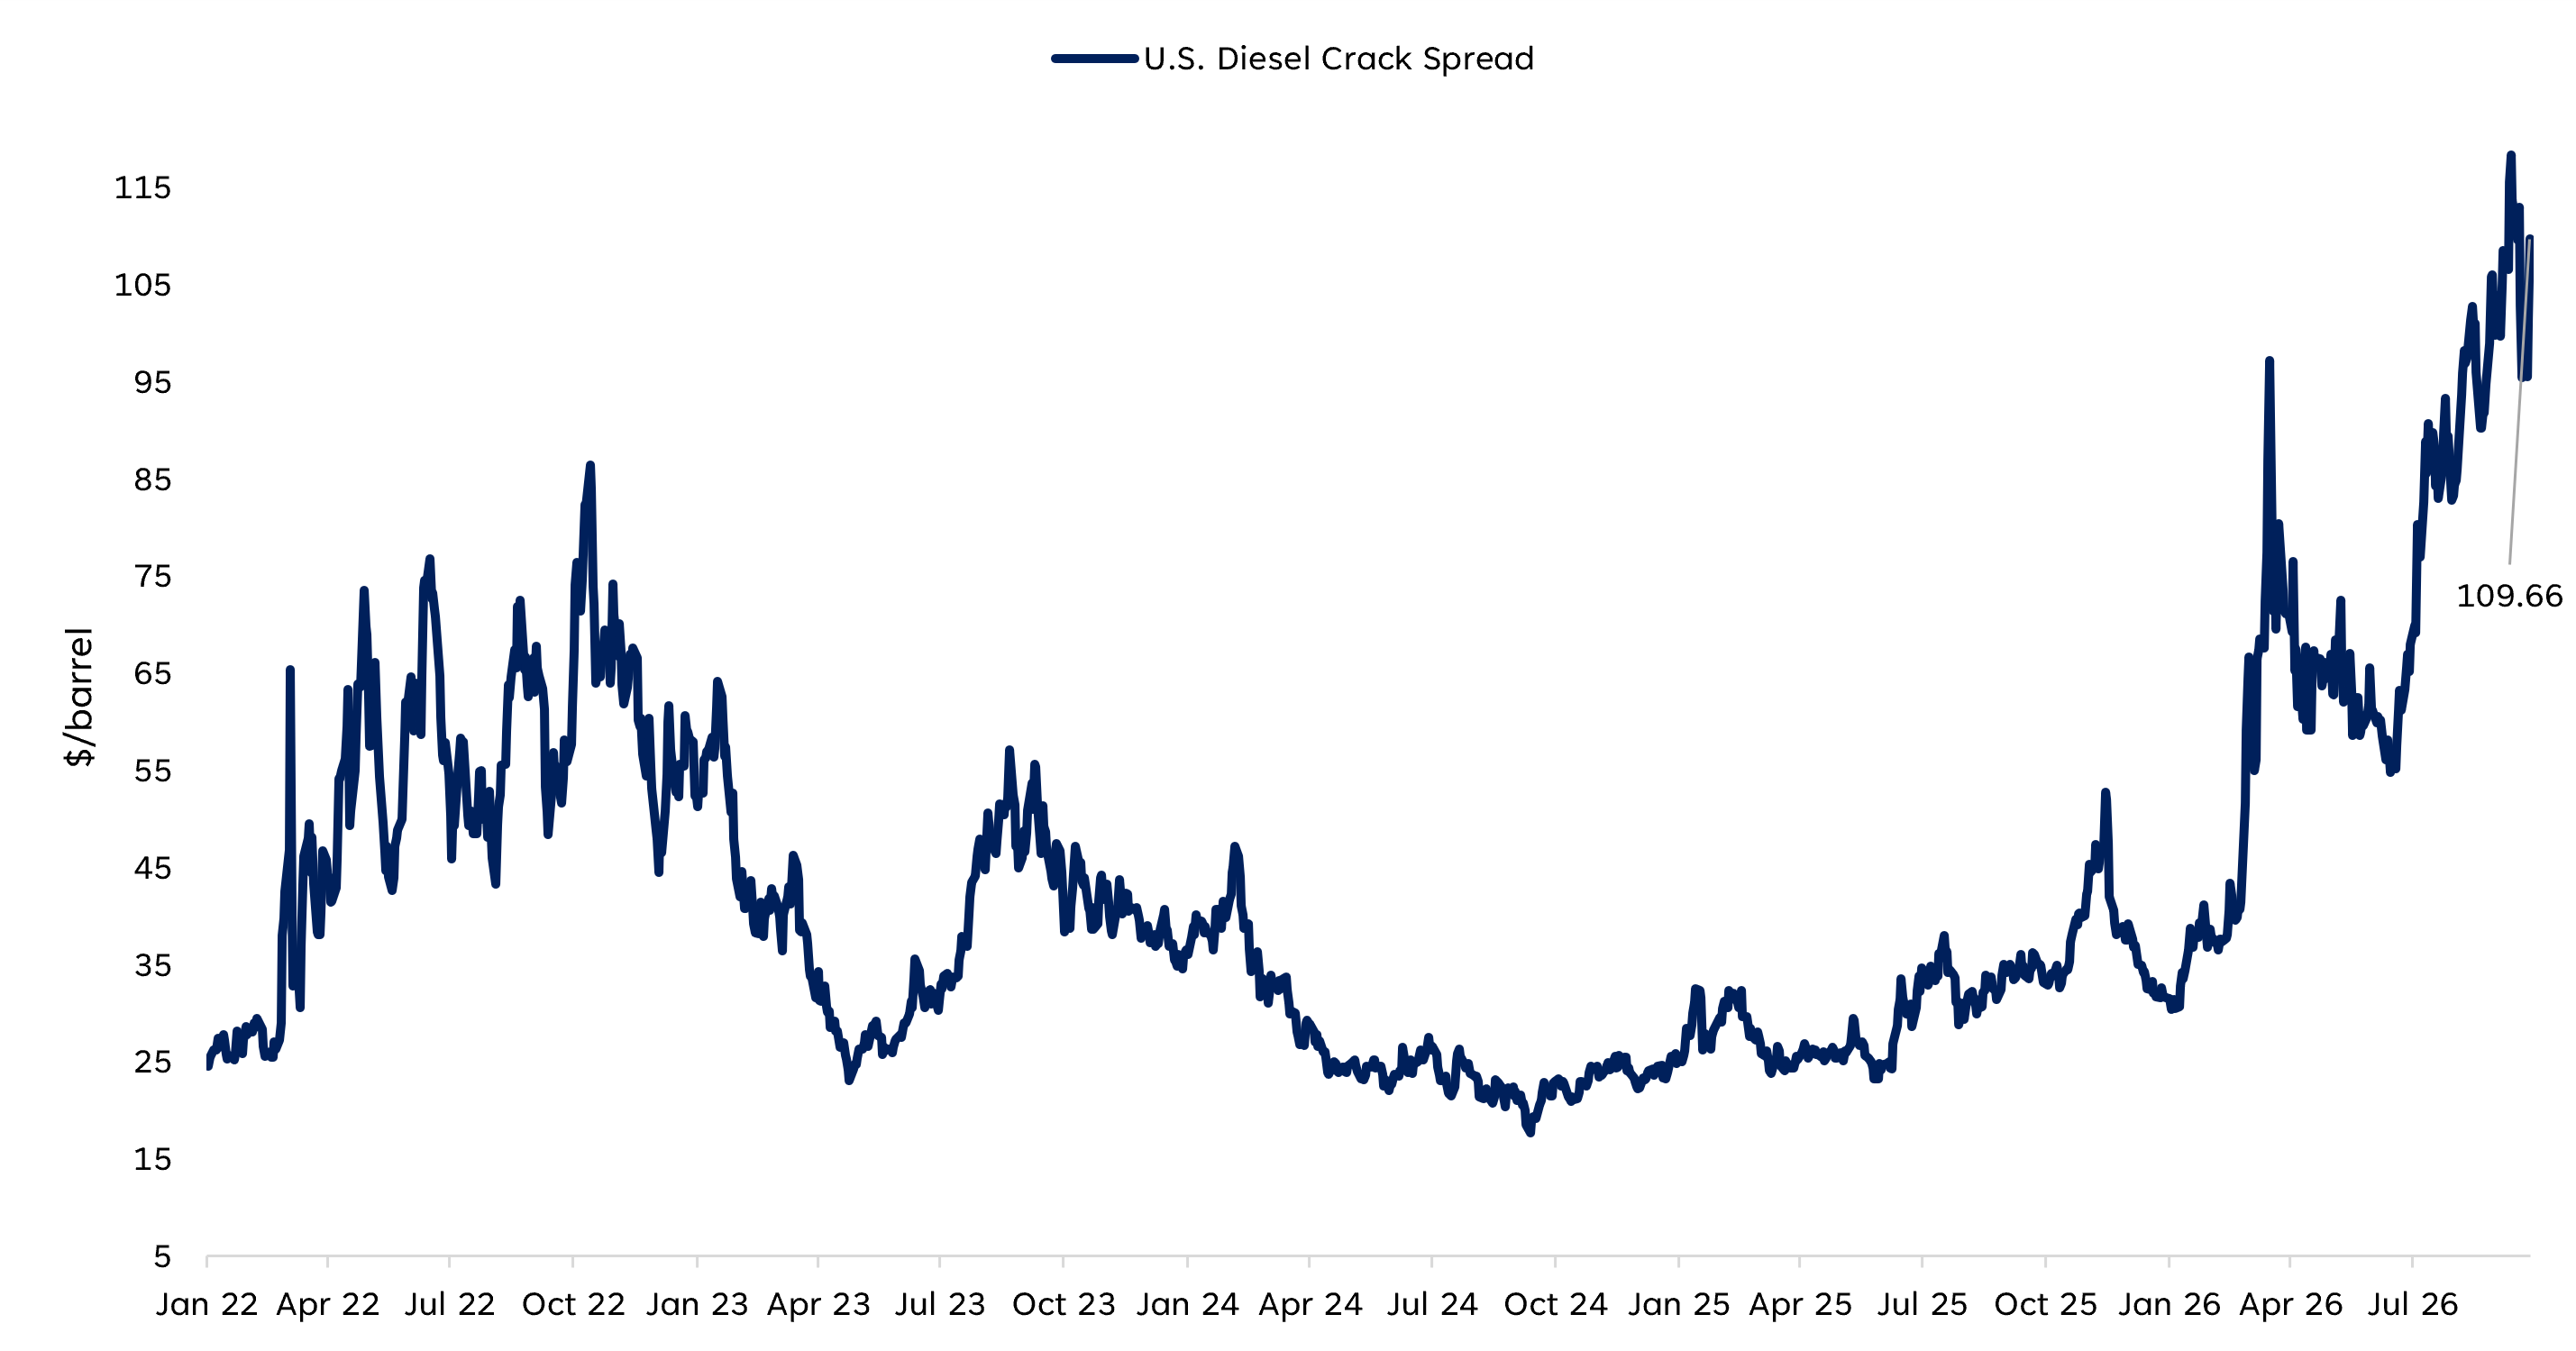
Source: LPL Research, Bloomberg 09/30/2026
Disclosures: All indexes are unmanaged and cannot be invested in directly. Past performance is no guarantee of future results.
Not everyone drives a diesel vehicle, or heats their home with oil, so why do record diesel crack spreads matter to markets? Often described as the lifeblood of the global economy, diesel is a critical input for trucking, rail transportation, agriculture, construction, and industrial activity. In short, higher diesel prices raise the cost of moving goods, which can translate into inflation. This, in turn, can also influence central bank thinking by complicating the ongoing battles against sticky services inflation at the Federal Reserve, the European Central Bank, and the Bank of England.
At the same time, crack spreads also point to further tightening in the fuel and energy markets. While crude prices faced an initial spike, corrected lower following the June memorandum of understanding (MOU) and jumped again in September, crack spreads have remained elevated throughout. This signals an important shift.
While crude oil shipping and available supply remains a key concern, elevated crack spreads suggest markets are becoming increasingly focused on refined product supply as diesel inventories have dwindled. Looming threats of a U.S. diesel export ban are a perfect illustration. As one of the world’s largest diesel suppliers, the U.S. has helped offset shortages abroad this year (especially in Europe), which has contributed to tighter domestic inventories, prompting policymakers to consider forcing product to remain stateside. While we won’t speculate on if a U.S. diesel ban will be implemented or not, if enacted it may only provide short-term relief to domestic prices, and drive price spikes and supply crunches in Europe and some Latin American nations.
Conclusion
While U.S. diesel crack spreads have come off their mid-September highs, they remain over double their five-year average. With autumn harvest activity ramping up across the Northern Hemisphere, spring planting beginning in parts of the Southern Hemisphere, and winter heating demand approaching, diesel markets may remain under pressure. This leaves some upside risk for inflation before it improves, could create a headwind for the business side of the economy, and may further complicate the Fed’s rate path. Plus, certain pockets of the equity market may face headwinds or tailwinds as near-record diesel prices hit shares of companies that keep the economy moving, while refiners benefit from strong margins (we discussed energy equities and crack spreads in depth earlier this year in Beyond the Numbers)
Bottom line, the market’s focus appears to be shifting from crude supply risk to refined-product scarcity, with crack spreads acting as the clearest signal of that transition. Considering the long-term trend of falling U.S. refinery counts and rising replacement costs, correcting elevated crack spreads may not be easy and uncertainty around the diesel export ban debate on Capitol Hill adds a near-term policy uncertainty layer on top of an already structurally tight market. As all eyes return to the Fed later this month and rapidly approaching midterm elections, crack spreads are likely to remain an important barometer of inflation pressures, energy market stress, and broader economic activity.