
by Carl Tannenbaum, Chief Economist, Northern Trust
I typically avoid business books when I am on vacation. But I made an exception during our sojourn last month for Andrew Ross Sorkin’s 1929. Nearly a century after the Great Crash, that era is still being studied for lessons that might be relevant in the current day. The potential for financial instability is ever-present.
Sorkin’s work isn’t the most authoritative account of the economic and financial events of that time: John Kenneth Galbraith’s The Great Crash, 1929, published in 1955, provides better background on what happened before and after that fateful October. Sorkin focuses more on the prominent personalities involved, from bankers to speculators and government officials. Even Winston Churchill makes a cameo.
Here are the main things I took away from the reading.
- Bubbles are only obvious in retrospect. The market excesses of the 1920s are apparent from the distance of history, but they were not clear in the moment. The hot stocks of the 1920s were new technology companies like RCA that promised to transform the economy. Traditional models were deemed inadequate to project the performance and valuation of these kinds of firms. There were voices that suggested that markets were overdone, and speculators who profited handsomely when this was proven true. But they were in the great minority.
- The Federal Reserve performed very poorly during the crisis. The Fed was a relatively young institution at the time, having been chartered in 1913 to foster financial stability. Sorkin describes an institution that was very much in the background during the crash, more intent on teaching lessons on the evils of excessive leverage and moral hazard than taking steps to limit the damage.
Years later, Anna Schwarz and Milton Friedman found that the Fed had presided over a huge contraction of credit. While the reserves supplied by the Fed to the economy continued to grow, the conservatism of lenders and the mass failure of financial institutions resulted in a credit crunch that made the situation much worse.
Subsequent research by Ben Bernanke confirmed this conclusion, and informed the Fed’s response to the 2008 financial crisis. Facing criticism over the moral hazard raised by his actions, Bernanke famously observed that “There are no atheists in foxholes, and no ideologues in financial crises.”
A recounting of 1929 highlights a broad series of failures.
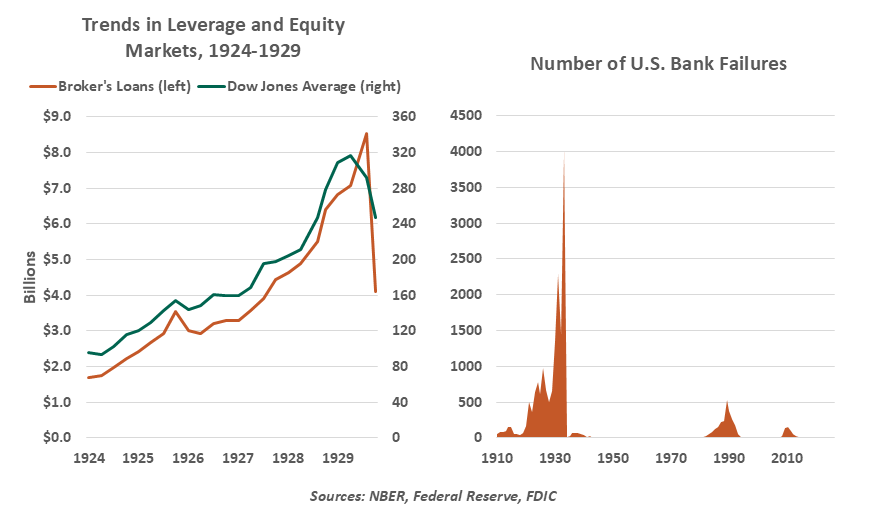
- Financial regulation was completely ineffectual. Bank failures in the United States had been rising in the years before 1929, revealing poor regulatory oversight. Securities markets were largely self-regulated by the major exchanges, creating a significant conflict of interest. The association of commercial banking and investment banking was unhealthy.
In the wake of the Great Crash, government supervision of finance was expanded. The Federal Deposit Insurance Corporation (FDIC) was chartered in 1933 and the Securities and Exchange Commission was created in 1934. The FDIC took a lead in overseeing smaller banks around the country, which had not been well-looked after by state regulators.
Ever since, periods of heavy regulation have typically seen few bank failures and periods of deregulation have seen more. We are in the midst of one of the latter episodes, which has raised concern in some corners. Federal Reserve Governor Michael Barr recently gave a speech ominously entitled: “Deregulating in a Financial Boom: What Could Go Wrong?”
During his book tour, Sorkin was asked if the timing of publication could be taken as any kind of warning about current market circumstances. He, and I, are very reluctant to make that association. But the experience of 1929 should not be lost on investors and institutions as they operate in the present day.
Copyright © Northern Trust